Almost two-thirds of fund groups (65%) expect the use of performance fees on equity funds to rise again in 2011 according to research by Skandia Investment Group (SIG).
The research, which is part of a broader study by SIG into the future of fund management, reveals that many global asset management firms believe the use of performance fees will increase across a range of asset classes this year. Equity funds and absolute return vehicles are expected to see the greatest increases, with 65% and 50% of those surveyed predicting rises across these two classes respectively.
The findings come at a time when the industry is also seeing investors change their focus from relative to absolute returns as a performance measure. While the figures show this is felt across the board, the biggest shift is among institutional investors (75%), compared with 58% of retail.
The PRF-related figures mirror those of a similar study carried out by SIG last year. At that time the number of share classes available with PRFs for sale in the UK was 1,433, according to figures from Morningstar. This number is now 1,952 – a rise of 36%. The total number of share classes available for sale in the UK is currently 19,616.
The findings also suggest that the introduction of more PRFs will be accompanied by a fall in fixed fees in some areas of the market, which the majority (58%) of respondents to the survey believe are under increasing pressure from the rise of passive products such as ETFs.
The study, now in its second year, questioned 40 fund management groups with combined assets under management of over $2 trillion. Based around the world, the groups were asked about their views on a range of areas and issues pertinent to the future of the asset management industry.
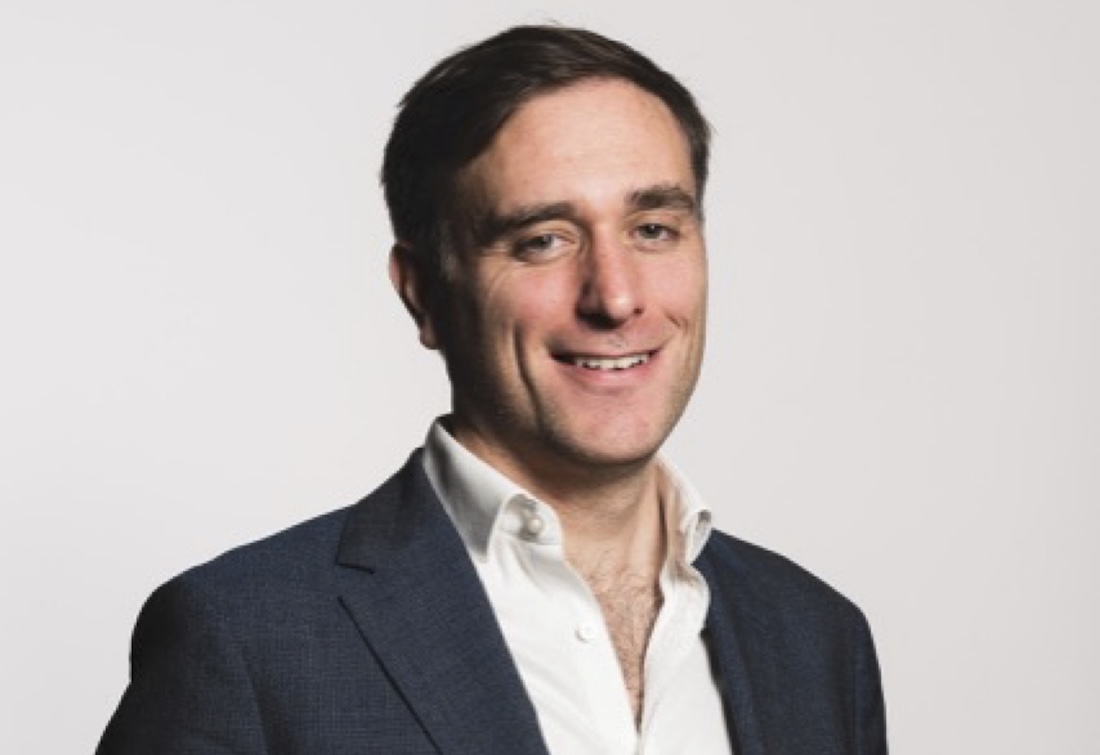
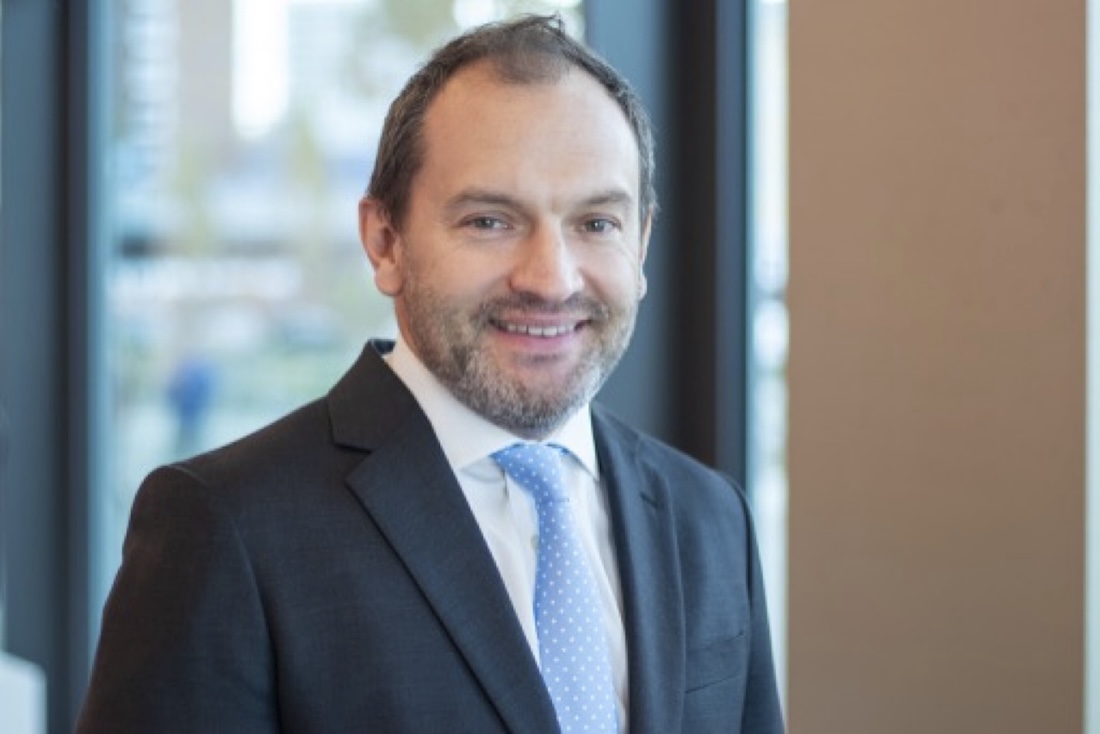
“With asset managers under continued pressure to demonstrate value for investors, combined with increasing pressure from low cost new entrants and low cost alternative solutions such as ETFs, we expect to see fees polarise," says James Millard (pictured), CIO at SIG. “While our research clearly shows the industry expects to see the use of performance fees increase further over the next 12 months, in some areas of the market annual management charges will be under pressure as a direct result of the rise of passive products including ETFs.
“In SIG’s view the increased availability of low cost sources of beta, the increased client demand for absolute returns after recent market volatility, and the rarity of genuine alpha is driving the polarisation in fees demonstrated by the asset managers surveyed.
“However, whatever happens, the overriding need is for the industry to ensure all fee structures are open and transparent so that investors understand exactly what they are signing up to.”