


Marina Gardiner, Research Editor, Elston Consulting, writes that since the “polycrises” of recent years, we are learning to live with inflation and live with volatility. Ensuring that a portfolio is sensibly allocated and diversified should help to mitigate the adverse effects of political or economic shocks.
A properly diversified approach designed to fare reasonably in all market conditions is known as an ‘All-Weather’ strategy.
What is an all-weather strategy?
The original “all weather” strategy was the “Permanent Portfolio” developed by Harry Browne in 1981 consisting of an equal weight allocation to equities, bonds, cash and gold.
The best known “all weather” strategy was pioneered by Ray Dalio of Bridgewater Associates in 1996 and consisted of an equal risk contribution (also known as risk parity) to core asset classes.
In the UK, Targeted Absolute Return (TAR) funds are also often described as “all weather” strategies because they are aiming to give positive rolling returns over a given time period.
What’s inside an all-weather strategy
What’s inside an all-weather strategy can vary depending on the strategy, fund and manager. What makes an all-weather strategy and indeed any alternatives allocation successful is that it has:
· Positive rolling returns over a given time frame, for example three-five years
· Limited downside risk
· Low correlation with both equities and bonds
Constructing an Alternatives allocation
Alternatives have previously been limited to Property or Infrastructure. We believe it deserves a broader pallet. We divide the alternatives universe into two distinct categories:
- Alternative assets (“Different Things”): This includes tangible or specialized exposures like infrastructure, gold, commodities, and property. We make a clear distinction between physical property and property securities. While they share similar economic drivers over the long term, they offer different trade-offs regarding liquidity and reported volatility—the latter often being a result of how frequently they are valued.
- Alternative strategies (“Doing Things Differently”): This refers to investment methods rather than just the underlying assets. Absolute return funds, for instance, might hold traditional stocks or bonds but apply risk management overlays to target a specific performance hurdle and mitigate losses. Risk-weighted and long-short equity models also sit within this bracket.
Delivering an alternatives allocation with Avastra
Elston consults to the managers of the VT Avastra Global Diversified Assets fund and provides asset allocation research ideas, correlation analysis and risk analytics to aid that quest for diversification. The fund provides both asset-based and risk-based diversification to deliver an all-weather style approach. It provides a one-stop-shop for an alternatives allocation. It is actively managed allocating between alternative assets and alternative strategies outlined above. The underlying holdings are all daily dealing and highly liquid to avoid any valuation mismatches or liquidity traps common to other types of alternative funds.
That liquidity also gives the fund the agility to adapt, when the facts change. It currently has exposure to property, commodities, absolute return strategies, and money market instruments.
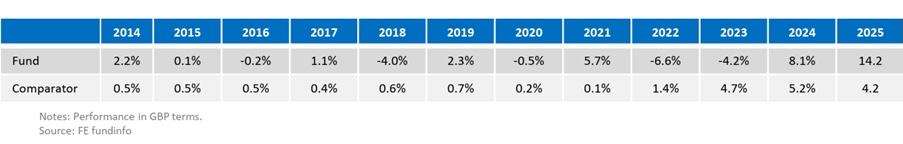
Delivering absolute returns: VT Avastra Global Diversified Assets fund calendar year performance vs SONIA Compounded
Considerations for sizing an allocation to an all-weather alternatives allocation
When considering an alternatives allocation to introduce an all-weather component to a multi-asset portfolio, three criteria are key:
- Return contribution: the strategy’s rolling returns should be steady.
- Risk contribution: the volatility and downside risk of a strategy should be comparable to, or lower than, the rest of the portfolio.
- Correlation: this is the least cited but most important metric. If a selection of “alternative” holdings behaves exactly like the equity or bond components during a market shift, they offer diversification in name only. For true benefit, they must exhibit low or zero correlation with traditional assets. Combining uncorrelated assets allows the total portfolio risk to be lower than the sum of its individual parts – described as the only “free lunch” of investing.
What are the options for UK-based advisers
For advisers looking to introduce an all-weather diversifier into a multi-asset portfolios, we propose that they look at the Targeted Absolute Return sector and evaluate based on the following metrics
- Consistent rolling positive return premium to SONIA hurdle rate over last 3 and 5 years
- Consistent rolling positive returns relative to sector over last 3 and 5 years
- Limited downside risk/Value at Risk – at similar or lower level than main Bond exposure
- Low beta/low correlation to both equities and bonds for true diversification
We are learning to live with volatility. That means frequent changes of the market weather. In that context, investing part of the non-equity allocation in an all-weather strategy seems prudent. But strategy selection is key.




